Check Your Costs Early With a Property Loan Calculator Before You Apply
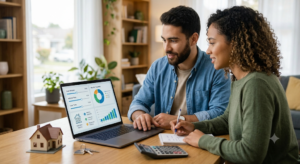
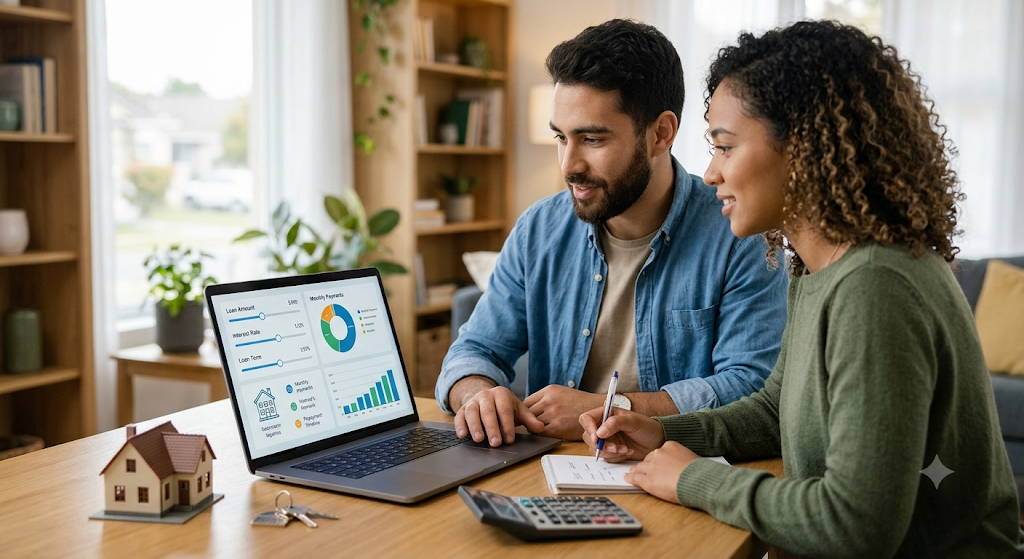
When considering a property purchase, one of the most essential steps in the process is understanding your financial obligations. A property loan calculator can be an invaluable tool, helping you estimate monthly payments, total interest costs, and the overall affordability of your mortgage. Here’s why you should leverage this tool before applying for a loan.
Why Use a Property Loan Calculator?
- Understand Your Budget: A property loan calculator helps you determine how much you can afford. By inputting variables such as loan amount, interest rate, and tenure, you gain insight into your financial landscape.
- Compare Loan Options: With a calculator, you can compare different loan scenarios, including variable vs. fixed interest rates and varying loan terms. This comparison enables you to choose the best financial product that meets your needs.
- Explore Agricultural Loan Schemes: If you’re looking to finance agricultural properties, understanding the nuances of agricultural loan schemes is critical. Some schemes may offer better terms or lower interest rates specifically for farmers and agricultural businesses. Using a property loan calculator can help you understand how these special loans will impact your finances.
- Avoid Surprises: Knowing your potential monthly payments in advance can help prevent any surprises when the time comes to secure the mortgage. This foresight allows you to budget effectively, ensuring you’re prepared for ongoing payments.
- Adjust Parameters Easily: One of the biggest advantages of a property loan calculator is its flexibility. You can easily adjust variables to see how changes, such as a higher down payment or a lower interest rate, can impact your financial situation.
Key Considerations Before You Apply
– Credit Score: Your credit score plays a significant role in loan approvals and interest rates. Ensure you check your credit report and address any discrepancies before applying.
– Down Payment: The amount you can put down upfront will affect your loan-to-value (LTV) ratio, which in turn influences your interest rates.
– Loan Terms: Familiarize yourself with the different types of loans available in the market to choose one that aligns with your financial goals.
– Fees and Other Costs: Remember to account for additional fees, such as closing costs, property taxes, and homeowners insurance when using your property loan calculator.
In conclusion, using a property loan calculator is a proactive step towards making informed financial decisions. It can simplify the often-complex process of mortgage applications, increase your confidence, and help ensure you’re not overextending financially.
For more tailored financial advice, consider consulting with a financial advisor to explore your options, including specialized agricultural loan schemes if relevant to your purchase.
Related Links
- Property Loan Calculator
- Agricultural Loan Schemes
By taking the time to assess your costs early on, you can proceed with your property purchase with greater clarity and security.