Magnesium Oxide Market to Reach USD 13.51 Billion by 2034, Driven by Industrial Demand
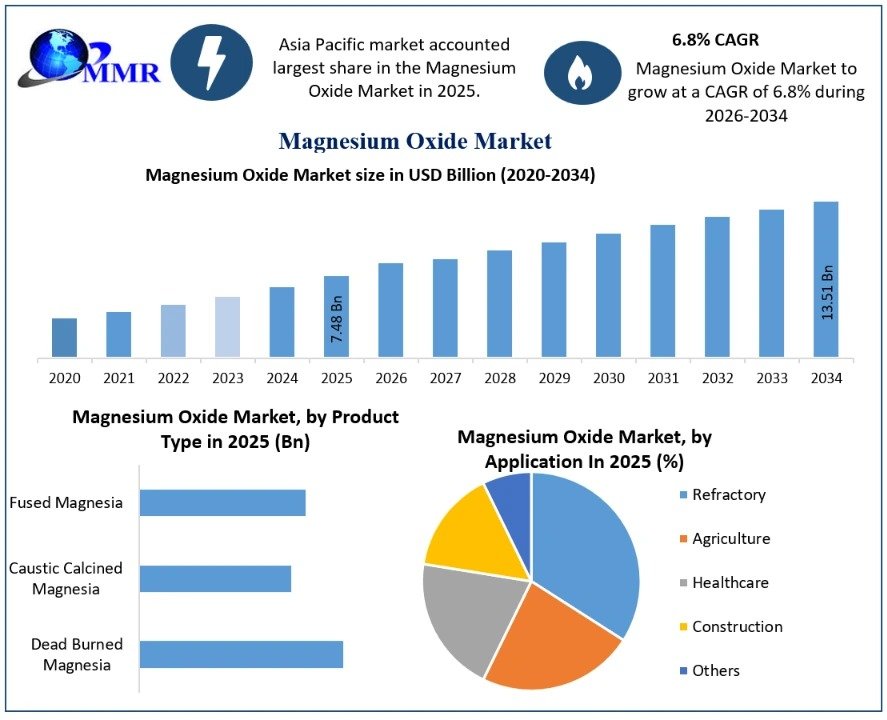
The Magnesium Oxide Market is poised for sustained growth as demand strengthens across steelmaking, construction, agriculture, chemicals and environmental applications. Valued at USD 7.48 billion in 2025, the market is projected to reach nearly USD 13.51 billion by 2034, registering a CAGR of 6.8% from 2026 to 2034. The outlook reflects magnesium oxide’s versatility and high-temperature stability.
Market Estimation, Growth Drivers and Opportunities
Magnesium oxide (MgO), also known as magnesia, is valued for its refractory performance, thermal conductivity, chemical stability and insulating properties. Demand is linked to durable materials for furnaces, kilns and industrial reactors. Steel, cement, glass and non-ferrous metal producers use MgO refractories to withstand extreme temperatures. Industrialisation and infrastructure development are key growth drivers.
Agriculture, fertilisers, animal feed, chemicals and wastewater treatment provide additional demand. Opportunities are emerging in high-purity grades, engineered materials and nanocrystalline MgO used as a recyclable catalyst. Improvements in purity, controlled reactivity and energy efficiency could open higher-value applications, although production costs and environmental compliance remain challenges.
United States Market: Trends and Investment in 2025
The United States remained an important market in 2025, supported by industrial and agricultural demand. RHI Magnesita completed its acquisition of US-based Resco Group in January 2025 for approximately USD 410 million. The deal expanded its North American refractory footprint and local supply strategy. In August 2025, Martin Marietta Materials completed its acquisition of Premier Magnesia, a specialist producer of magnesia and caustic-calcined magnesium oxide. The deal broadened its specialty minerals portfolio and domestic supply capabilities. Both investments highlight the importance of regional production and reliable supply.
Get Your Free Sample Report Link : https://www.maximizemarketresearch.com/request-sample/28350/
Market Segmentation: Leading Segments
By product type, dead-burned magnesia is expected to hold the largest market share. It offers high density, purity and low reactivity for magnesia-carbon bricks, monolithic refractories, castables and ceramics.
By application, refractory is the leading demand segment, supported by use in iron and steel production, cement kilns, glass furnaces and other high-temperature equipment. It helps extend furnace life and minimise downtime.
Competitive Analysis: Leading Companies
Competition centres on resource access, scale, quality and technical expertise. Five prominent companies are:
RHI Magnesita N.V. is a major global refractory producer. Its 2025 Resco acquisition strengthened North American operations and expanded customer reach in petrochemicals, cement and aluminium. Local manufacturing can improve delivery reliability.
Martin Marietta Materials strengthened its specialty magnesia position through its 2025 acquisition of Premier Magnesia. The addition expands its reach in environmental, agricultural and industrial markets.
Grecian Magnesite S.A. is an established producer with magnesite mining and processing capabilities. Its portfolio includes caustic-calcined and dead-burned magnesia. Efficiency and specialised grades can support its market position.
Premier Magnesia LLC, now part of Martin Marietta, is known for specialty magnesia and caustic-calcined magnesium oxide. Its capabilities strengthen the parent company’s environmental, agricultural and industrial offering.
Ube Industries Ltd. supplies magnesium oxide and advanced materials. Its quality-controlled materials serve customers requiring consistent, specialised grades.
Regional Analysis: Key Countries
The report identifies Asia Pacific as the largest regional market, although it does not publish individual market-share percentages for the countries listed here. In the United States, environmental regulations and investment in domestic industrial capacity encourage demand for treatment chemicals and dependable mineral supply. China’s industrial modernisation and energy-efficiency measures support upgrades in steel and refractory production. Germany and France are influenced by European industrial-emissions and circular-economy frameworks, while Japan’s Green Transformation agenda encourages efficient industrial technologies and advanced materials.
United States: Domestic investment and demand from industrial, agricultural and environmental applications support market development. USGS data for 2024 estimated domestic magnesium-compound production at 430,000 metric tons of MgO content and apparent consumption at 890,000 metric tons, indicating continued import reliance. This supply gap strengthens the case for domestic capacity and resilient sourcing.
China: China is a major centre for magnesite resources, processing and steel production. Its large refractory-consuming industries and manufacturing base support substantial MgO demand. Industrial upgrading is encouraging process efficiency.
Germany: Steel, chemicals, glass, ceramics and advanced manufacturing support demand. Efficiency and decarbonisation goals favour durable, high-performance refractories.
United Kingdom and France: Steelmaking, construction materials, chemicals and environmental management provide established end-use markets. Modernisation can sustain demand for refractory and specialty magnesia.
Japan: Advanced steel, electronics, ceramics and chemical industries require consistent, high-purity materials. Advanced manufacturing supports specialised MgO grades.
Key Players
Other notable participants include Kumas Magnesite Industry Inc., Xinyang Mineral Group, Israel Chemicals Ltd., SMZ a.s. Jelsava, Tateho Chemicals Industries, Baymag Inc., Nedmag Industries, Industrias Peniles, Imerys and Magnezit Group.
Why This Market Matters Now
Magnesium oxide is essential to industries underpinning infrastructure, manufacturing, food production and environmental services. Growth is reinforced by industrial expansion, refractory replacement, investment in domestic supply chains and demand for specialised materials. Producers combining reliable mineral sourcing with efficient processing, technical innovation and customer-focused products are positioned to benefit from long-term market expansion.
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company providing reliable, data-focused and practical business insights. It serves healthcare, technology, automotive, electronics, chemicals and consumer goods, helping organizations identify opportunities through forecasts, competitive analysis and strategic consulting.
Contact Us
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com